worldsteel short range outlook October 2026
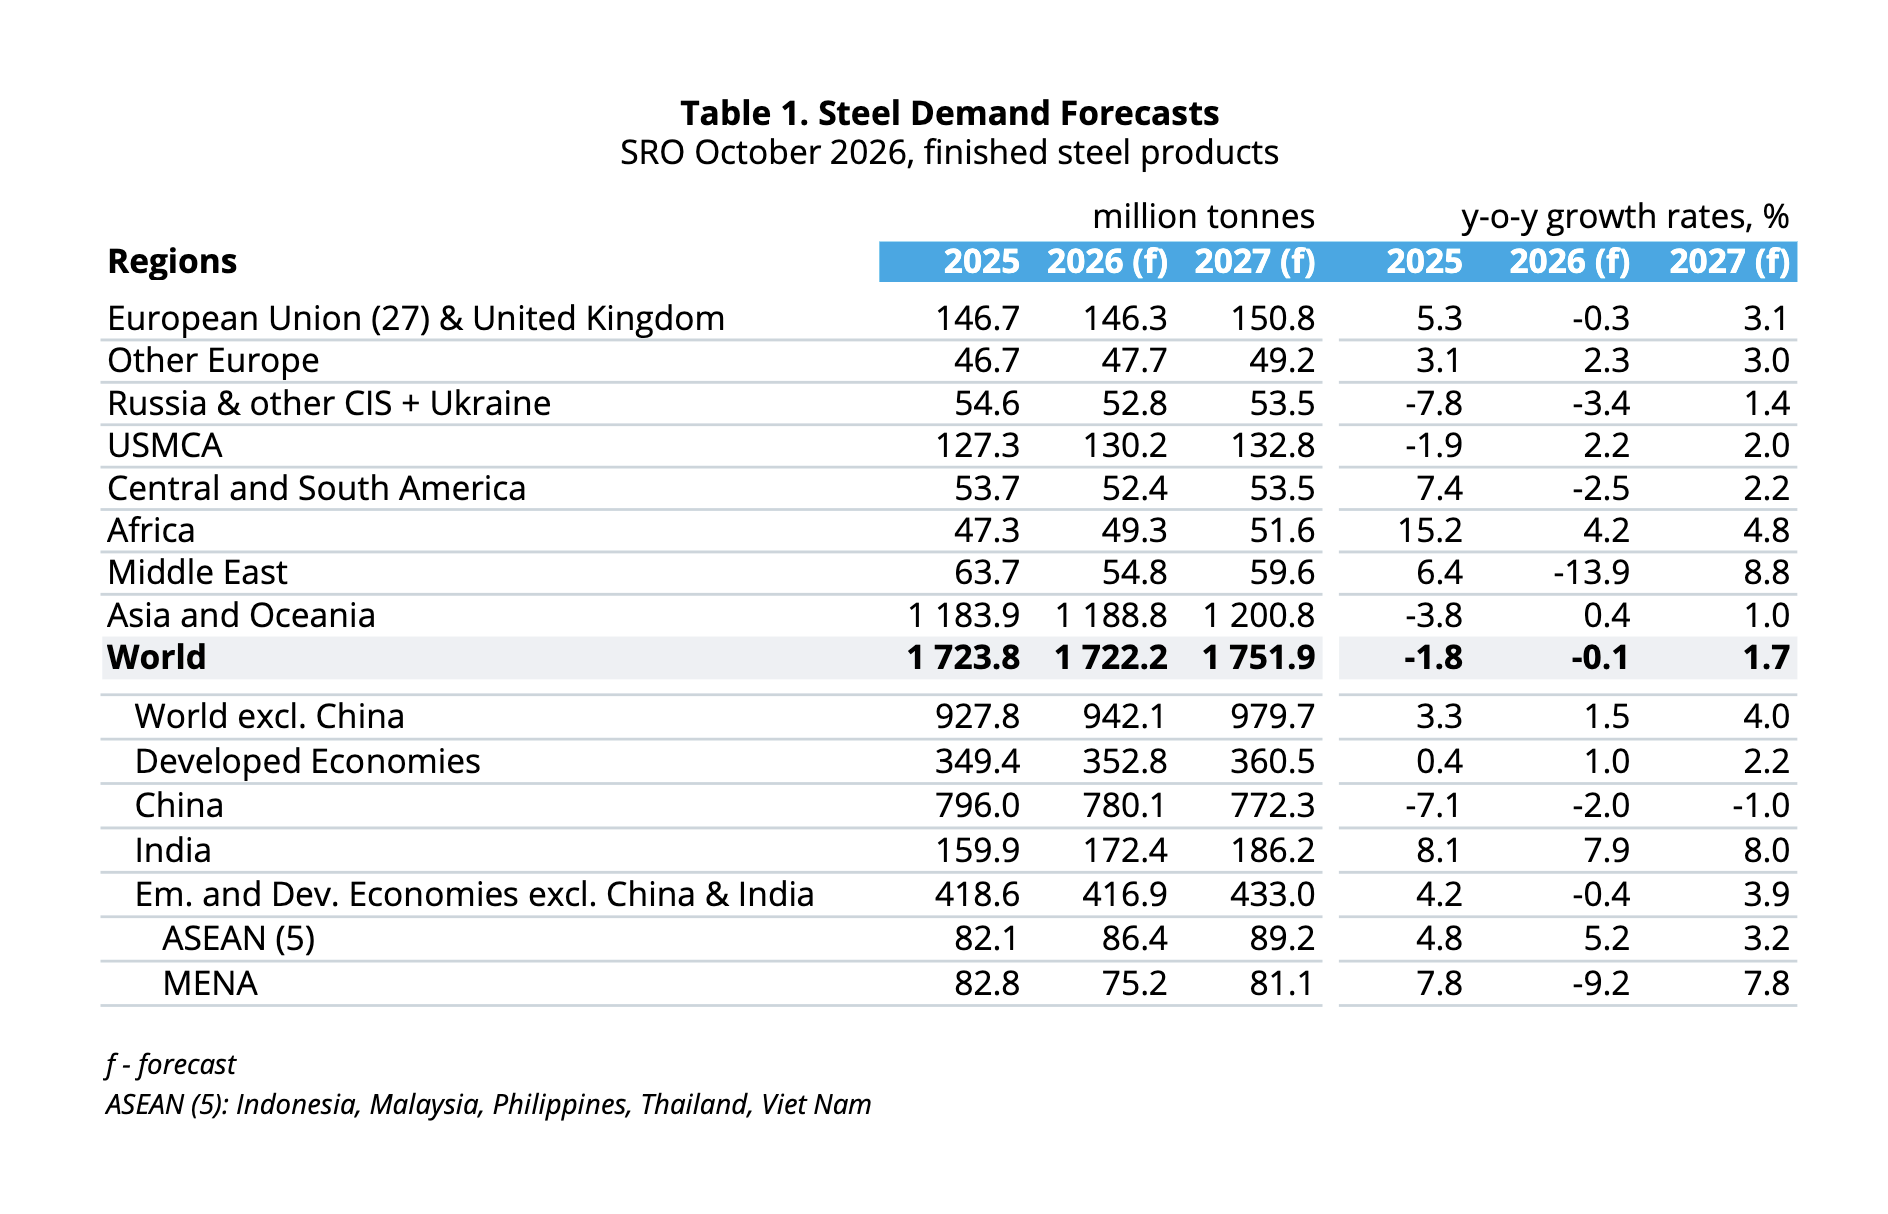
The World Steel Association (worldsteel) has released its short range outlook (SRO) steel demand forecast for 2026 and 2027. Compared with 2025, worldsteel forecasts that global steel demand will remain essentially unchanged in 2026 at 1722 Mt, before returning to growth of 1.7% in 2027 to reach 1752Mt.
Alfonso Hidalgo De Calcerrada, chair of the worldsteel Economics Committee, said, “The trajectory we set out in April holds, but the anticipated recovery is proving slower and more gradual than we had expected. Global steel demand is now forecast to be flat in 2026 rather than to grow modestly, and to grow by 1.7% in 2027 rather than 2.2%. Almost the whole of that revision is a China story. Outside China, demand grows by 1.5% this year and accelerates to 4.0% in 2027 — precisely the rate we projected six months ago, and one rarely seen in recent times. The recovery we described in April is therefore not weaker; its momentum is being masked by the scale of China’s structural contraction and compounded by energy-market disruptions stemming from ongoing instability in the Middle East.
One of the most important messages coming from our October 2026 forecasts is a reaffirmation of the expectations for a meaningful turnaround in developed world industrial activity and steel demand in 2027. Following a stabilisation over 2025–2026, developed world industrial activity is expected to show a broad-based recovery in 2027, which is underpinned by growth in AI-related investments, defence and energy transition spending, improving incomes and a supportive policy framework. With the developed world growing alongside developing economies excluding China, the outlook for steel demand growth outside China reaches 4.0% in 2027. Growth on that scale, and that broadly based, has been rare in recent years and is an encouraging signal for the steel industry and the wider economy.
This outlook reflects data available as of early September 2026. In April we assumed the conflict in the Middle East would be resolved by June, and we warned that a longer conflict would force material downward revisions. The conflict has not been resolved, yet the initial hit to global activity has been less severe than we had assumed. Energy markets absorbed the disruption better than feared, and the major economies proved more resilient than our downside case implied. Yet, that resilience should not be mistaken for immunity. Where exposure is direct – most acutely across the Gulf – the economic damage is undeniable. While the global economy has absorbed the initial impact, its capacity to buffer subsequent disruptions appears increasingly depleted. For this reason, we maintain a measure of caution regarding the 2027 outlook.”
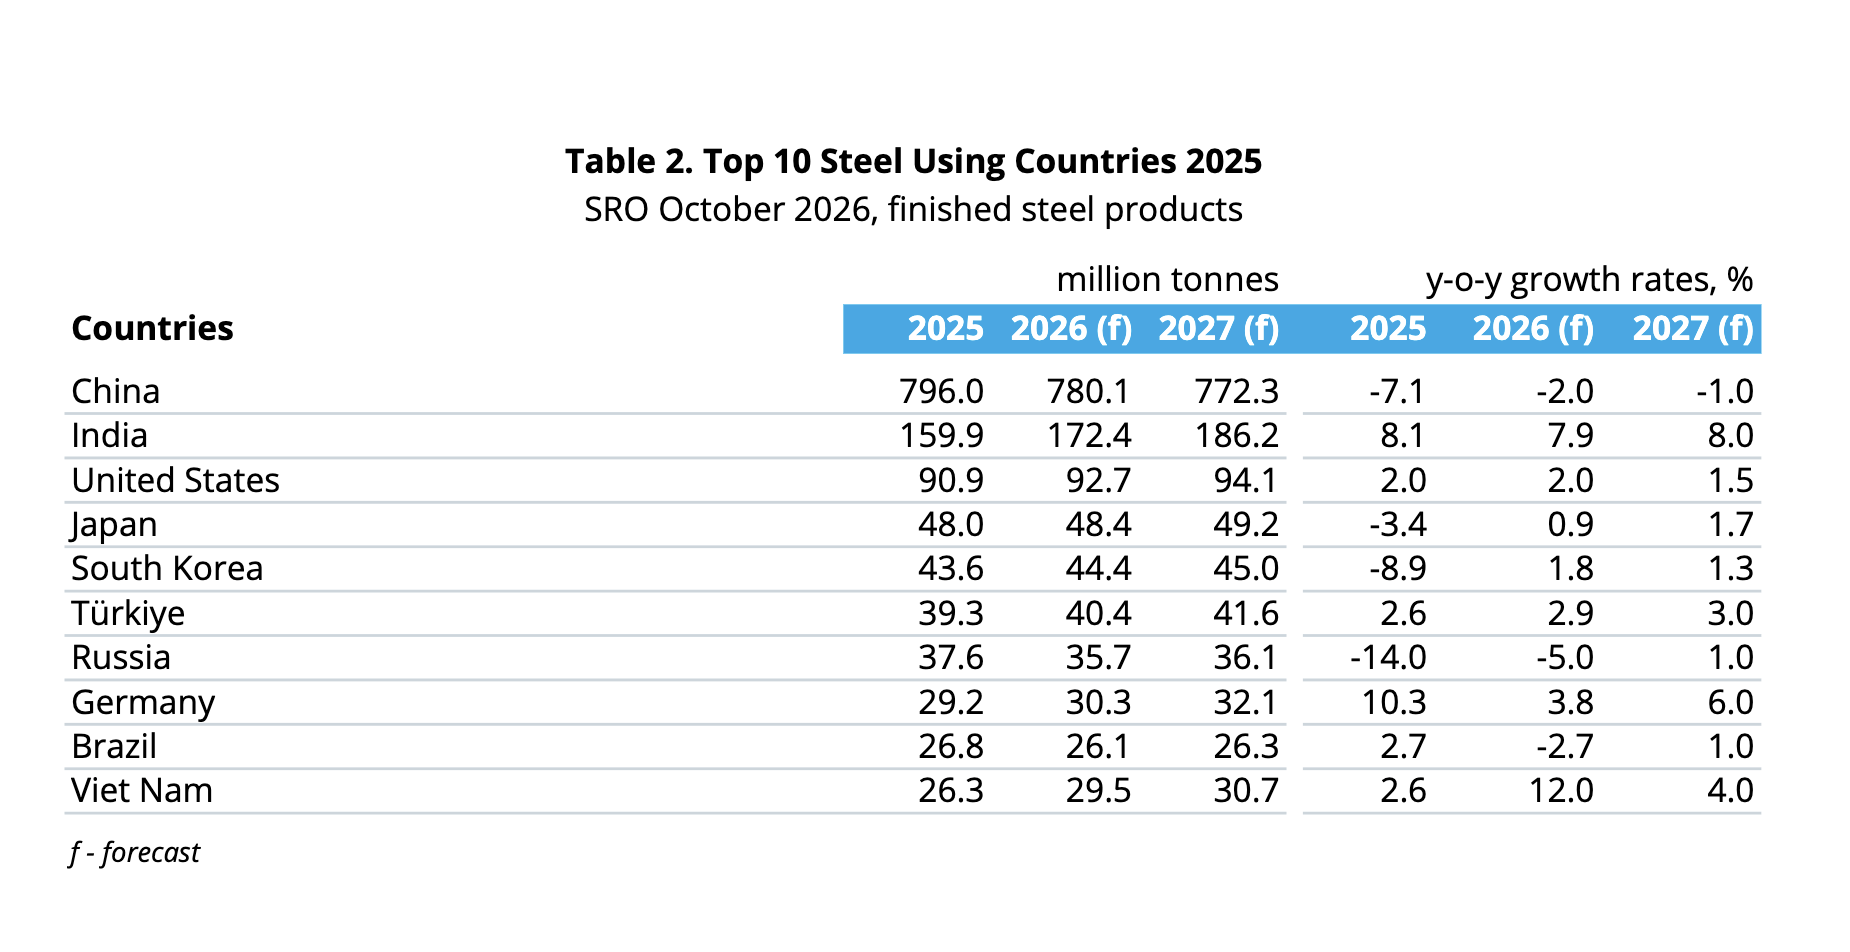
We now expect Chinese steel demand to contract by 2.0% in 2026, a downward revision from our April forecast. The property investment downturn has not decelerated as we had anticipated. Infrastructure investment, which we had expected to provide support this year, has instead remained in negative territory. Steel demand from manufacturing has continued to grow on the back of strong exports, but not by enough to offset the weaker than expected performance of real estate and infrastructure.
For 2027, we expect the contraction in China to narrow to 1.0%. The real estate downturn is expected to start decelerating while remaining negative, the government retains a cautious stance towards expanding infrastructure investment, and manufacturing should sustain moderate growth provided exports hold up. Trade frictions are, however, emerging as a significant risk.
Steel demand in developing economies excluding China is forecast to grow by 1.9% in 2026 and by 5.1% in 2027. The moderation this year, from the roughly 5% annual growth recorded in recent years, is driven by the Middle East, where regional conflict has reversed what had been one of the strongest growth stories in the global market. Elsewhere in the developing world, the underlying momentum is intact, and the 2027 rebound is driven by Developing Asia together with a recovery in the Middle East.
India remains the world’s fastest-growing major steel market, with demand forecast to expand by 7.9% in 2026 to 172.4Mt and by 8.0% in 2027 to 186.2Mt. Growth continues to be broad-based. Infrastructure-led construction remains the primary driver. Private real estate demand is robust. Healthy manufacturing growth, a substantial renewable energy project pipeline and continued expansion of manufacturing capacity are lifting both electrical and mechanical machinery, while automotive output is buoyed by domestic demand, export momentum and policy support.
The Gulf provides the clearest single demonstration of what the conflict has cost. GCC steel demand grew by 17.7% in 2025, propelled by economic diversification programmes, a healthy project pipeline and strength in housing activity in the KSA and the UAE. We now expect GCC demand to fall by about 11% in 2026, a sharp reversal of the trajectory we published in April. What we observe is not the destruction of demand but its deferral, as project awards, construction starts and financing decisions are pushed back while the security situation remains unresolved. On that reading, steel demand in the Gulf should recover strongly once the uncertainty clears, the Strait of Hormuz reopens and the supply chains normalise. Reflecting this optimistic scenario, we forecast a rebound of 11.3% in 2027, taking regional demand back to its 2025 level.
ASEAN-5 demand is now forecast to grow by 5.2% in 2026 before moderating to 3.2% in 2027. Vietnam is the standout: production and trade data point to a double-digit growth rate this year, taking the country’s apparent steel use to about 30 Mt for the first time, supported by a record volume of residential and commercial building under construction and a robust public investment programme.
Steel demand in the developed world is forecast to grow by 1.0% in 2026 and by 2.2% in 2027, following the stabilisation recorded in 2025. The scale of the recovery should be kept in perspective. The 2025 market was roughly 60 Mt, or 15%, smaller than in 2017–2018, and the growth we now forecast over 2026-2027 recovers only about 10 Mt of that gap. A full return to pre-crisis volumes remains a long-term endeavour.
We now expect EU apparent steel use to decline by 0.3% in 2026 before growing by 3.1% in 2027, a downward revision of 1.5 percentage points for this year. The 2025 outturn was stronger than we had forecast, but a significant part of that strength was stock building ahead of CBAM taking effect in 2026. Underlying conditions have also disappointed. The construction recovery is proving slower and more fragmented than expected, with residential permits showing signs of bottoming out while completions remain in recession, and automotive continues to drag. Sentiment is nonetheless improving, and we expect a meaningful recovery in the steel-using sectors from 2027, supported by infrastructure and defence spending under the new fiscal framework, improving real household income and civil engineering activity tied to energy and rail investment.
Steel demand in the United States is projected to grow by 2.0% in 2026. Growth has been underpinned by strong investment in data centres and energy infrastructure, including power generation, renewables, and oil and gas, together with incremental support from selected manufacturing sectors. ASU in the U.S. is expected to grow by approximately 1.5% in 2027. The U.S. economy is forecast to continue growing around trend, with steel demand growth expected to remain concentrated in non-residential construction, especially mega projects in infrastructure, energy, and selected manufacturing end markets rather than residential construction. Residential construction activity is expected to remain comparatively soft in 2027. Homebuilder sentiment remains subdued with elevated mortgage rates, affordability constraints, and high construction costs.
Japan and Korea are both set for modest recoveries after difficult years. Japanese steel demand is expected to grow by 0.9% in 2026 and 1.7% in 2027, as construction turns from a drag into a support and expanding corporate capital investment lifts machinery, while automotive remains under pressure. In Korea, demand is forecast to grow by 1.8% and 1.3% following a steep fall in 2025. Construction should find its floor and begin a partial recovery from the second half of 2026, while automotive production and shipbuilding activity return to modest growth. In both markets, the recovery is real but shallow, and neither returns to pre-downturn volumes within the forecast horizon.